How Long Does It Take for Universal Credit to Be Approved?
Universal Credit does not have a fixed approval timeframe, but most new claimants normally receive their first payment around five weeks after submitting their claim.
The Department for Work and Pensions (DWP) must check eligibility, verify identity and review the information provided before confirming entitlement.
The five-week period refers to the usual first-payment schedule, not a guaranteed approval deadline.
Some applications may be processed sooner, while others can take longer because of missing documents, additional eligibility checks or incomplete claimant commitments.
Understanding the difference between claim approval and payment timing can help applicants recognise delays and take the necessary steps to resolve them.
What Happens After You Submit a Universal Credit Application?
Once a Universal Credit application has been submitted, the DWP reviews the claimant’s circumstances to establish whether they qualify for financial support.
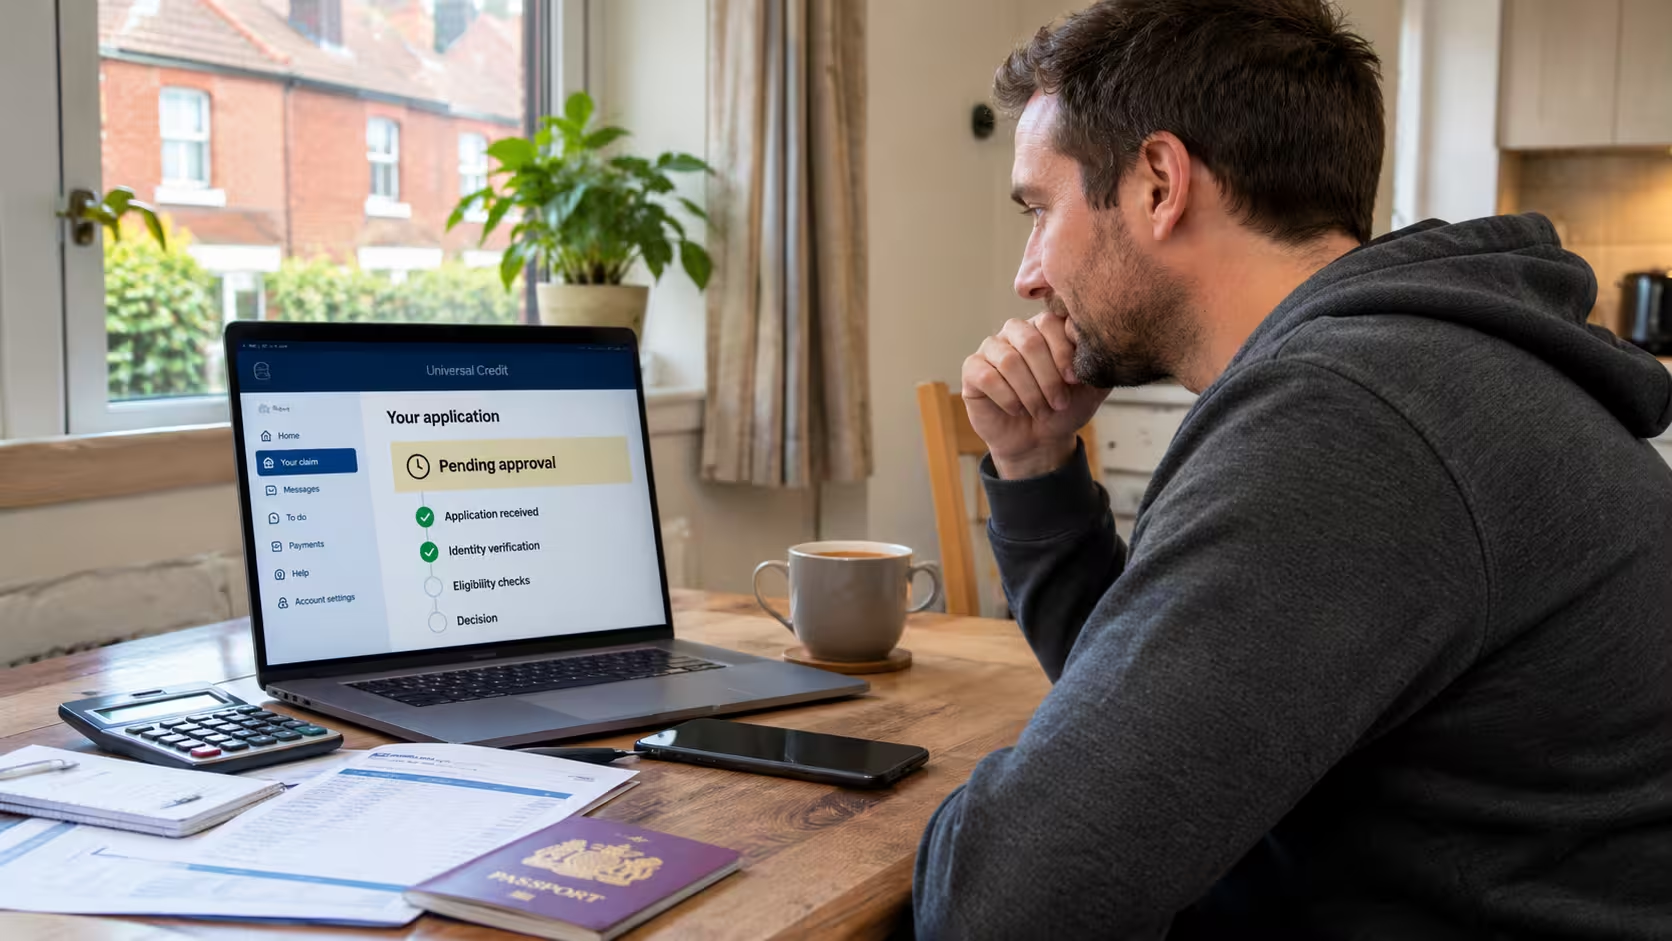
The process involves several stages, including verifying personal information, checking household income and confirming the applicant’s responsibilities.
Anyone preparing to make a claim should understand how to apply for Universal Credit and which information must be provided before submitting an application.
What Happens After Submitting Your Application?
After applying, claimants may need to complete the following steps:
- Application Review: The DWP examines the information submitted, including employment, household income, savings and living arrangements.
- Identity Verification: Applicants must confirm their identity using an accepted verification method.
- Document Submission: Additional evidence may be requested to confirm income, housing costs or other circumstances.
- Claimant Commitment: Most applicants must agree to responsibilities based on their personal circumstances before receiving payments.
- Eligibility Decision: The DWP determines whether the claimant qualifies for Universal Credit and calculates their entitlement.
The DWP may contact applicants during the first few weeks after submission. Messages and instructions usually appear in their Universal Credit online account.
How Long Does Identity Verification Take?
There is no guaranteed processing time for Universal Credit identity verification. The time required depends on whether an applicant can complete the checks online or needs further verification.
Successful online verification may remove the need for a full initial evidence interview. However, applicants who cannot verify their identity online may need an appointment or additional documents.
According to GOV.UK, identity verification methods include:
- Online Verification: Applicants provide information from accepted identity records.
- Documentary Evidence: Identification documents may be checked when online verification is unsuccessful.
- Face-to-Face Appointment: Applicants may be asked to attend a jobcentre or arrange another suitable appointment.
- Biographical Interview: The DWP may ask questions to confirm personal information.
For in-person identity checks, current DWP guidance generally requests one photographic identification document and two supplementary documents.
Alternative checks may be necessary where documents are unavailable.
Completing verification as quickly as possible can prevent unnecessary delays.
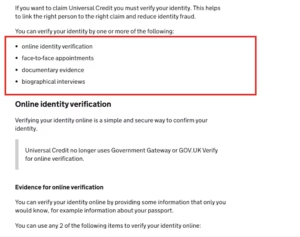
GOV.UK confirms the identity verification methods available to Universal Credit applicants, including online checks, documents and interviews.
When Does the DWP Make an Approval Decision?
The DWP makes an entitlement decision after completing the checks required for an individual claim.
There is no universal deadline that guarantees a decision within a particular number of days.
For straightforward applications, the necessary checks may be completed during the initial assessment period. However, the DWP may need additional time if information is missing or eligibility requires further investigation.
Applicants should regularly monitor their online account for outstanding tasks or requests for evidence.
How Long Does It Take to Receive Your First Universal Credit Payment?
Most successful Universal Credit applicants receive their first payment approximately five weeks after making their claim.
Universal Credit is calculated using monthly assessment periods, followed by a scheduled payment seven days after the assessment period ends.
The five-week waiting period does not mean that the DWP spends five weeks deciding whether someone is eligible.
Universal Credit Five-Week Payment Timeline
The following table explains the normal payment schedule.
Stage Timeframe What Happens
Application Submission Claim Date The applicant submits their completed claim
Initial Assessment Period One Calendar Month Income and household circumstances are assessed
Payment Schedule Seven Days After Assessment Ends The first payment is normally issued
First Payment Around Five Weeks Eligible claimants receive their Universal Credit
For example, someone who submits a claim on 10 November 2026 would normally have their first assessment period running from 10 November to 9 December.
Their first payment would ordinarily be scheduled for 16 December 2026, assuming the claim has been processed and entitlement established.
After the first payment, Universal Credit is normally paid on the same date each month. Payments due on weekends or bank holidays are generally made on the preceding working day.
Universal Credit is usually paid monthly in England and Wales. Claimants in Scotland can choose twice-monthly payments, while Northern Ireland generally offers twice-monthly payments with an option to receive them monthly.
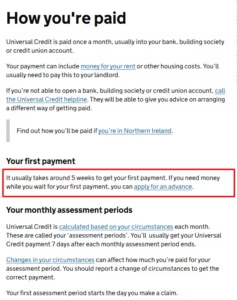
GOV.UK confirms that the first Universal Credit payment normally takes around five weeks, including a monthly assessment period and seven days before payment.
When Does the Assessment Period Start?
The first Universal Credit assessment period normally begins on the date the claimant submits their completed application.
It lasts one calendar month, rather than a fixed 30 days.
Simply creating an online account does not necessarily mean that a Universal Credit claim has been submitted.
The assessment period establishes the income and circumstances used to calculate entitlement. This is why Universal Credit is paid in arrears rather than immediately when an application is submitted.
Changes in earnings, household circumstances or other relevant information during this period can affect the amount eventually paid.
What Can Delay Universal Credit Approval?
Although the first payment normally arrives after approximately five weeks, some applications take longer because the DWP cannot complete all necessary checks.
Several issues can affect the progress of a claim.
Missing or Incorrect Information
Errors in an application may require the DWP to request further information.
Common examples include:
- Incorrect Personal Details: Names, dates of birth or National Insurance information do not match relevant records.
- Missing Income Information: Employment earnings, savings or other financial details need clarification.
- Incomplete Housing Evidence: The DWP requires further evidence of rent or tenancy arrangements.
- Unreported Household Changes: A change involving a partner, dependent child or address requires additional checks.
Missing housing evidence may affect the housing costs element without necessarily delaying every part of the claim.
Claimants should check their applications carefully and respond promptly whenever the DWP requests clarification.
Identity Verification And Document Issues
Identity verification problems can delay processing because the DWP must confirm that the claim belongs to the correct person.
A person may experience difficulties if their identification documents are unavailable, information does not match official records or they cannot complete online verification.
Applicants should follow the instructions in their Universal Credit account and arrange alternative verification when necessary.
Missed Appointments And Claimant Commitments
Some applicants must attend meetings with their work coach or provide further information before their claim can progress.
Most claimants must also accept their claimant commitment. Failure to accept it can result in the claim being stopped.
Missing appointments can have different consequences depending on the stage of the claim and the claimant’s circumstances.
For people already subject to work-related requirements, a Universal Credit missed appointment sanction may reduce payments if the DWP decides there was no good reason for missing the appointment.
Applicants who cannot attend should contact their work coach as soon as possible and explain the circumstances.
Changes In Circumstances And Additional Eligibility Checks
Some applications need additional checks because of the claimant’s residence, immigration status or financial circumstances.
For example, applicants who have recently moved to the UK may need to satisfy relevant residence and right-to-reside requirements.
Other circumstances requiring further investigation can include:
- Recent Employment Changes: New earnings or final salary payments need to be considered.
- Changes In Living Arrangements: Moving in with a partner or changing household circumstances affects entitlement.
- Savings And Capital Checks: The DWP needs additional information about money, investments or property.
- Residence Requirements: Applicants may need to provide evidence demonstrating that they meet the relevant conditions.
Additional checks do not automatically mean an application will be refused.
To minimise delays, claimants should provide accurate information, complete outstanding tasks, attend appointments and report changes promptly.
How Do You Know If Your Universal Credit Has Been Approved?
Applicants can check the progress of their Universal Credit claim using their online account.
The DWP normally communicates through journal messages, account notifications and requests for information.
How To Check Your Universal Credit Application Status?
Claimants can monitor their application by following these steps:
- Sign In To Your Account: Access the official Universal Credit online service.
- Check Your Journal: Look for messages from the DWP or a work coach.
- Review Your To-Do List: Identify documents, appointments or actions that still need completing.
- Check Your Payment Section: Look for an available payment statement showing the amount and scheduled date.
- Contact The DWP: Request clarification if the claim appears unresolved or important information is missing.
A payment statement showing an award and payment date is a useful indication that entitlement has been calculated.
However, an empty payment section does not automatically mean an application has been rejected.
What To Do If Your Application Is Still Being Processed?
If an application remains unresolved, the claimant should first check whether the DWP is waiting for evidence or an appointment.
They can then send a journal message asking whether any further information is required.
If they cannot access their account or need direct assistance, they can contact the Universal Credit helpline.
Universal Credit Helpline
- Telephone: 0800 328 5644
- Opening Hours: Monday To Friday, 8am To 6pm
- Official Website: https://www.gov.uk/universal-credit/contact-universal-credit
If the usual first-payment date is approaching and there is still no statement or decision, applicants should contact Universal Credit rather than assuming payment will arrive automatically.
What Happens If Your Universal Credit Application Is Rejected?
The DWP may refuse an application when the claimant does not meet the relevant eligibility requirements.
A refusal is different from an application that is still awaiting verification or additional information.
Common Reasons For Universal Credit Refusal
Eligibility problems may include:
- Excessive Savings: The claimant normally has more than £16,000 in assessable capital, unless a specific exception applies.
- Age Requirements: The applicant does not meet the usual age conditions or an applicable exception.
- Residence Requirements: The claimant does not satisfy the relevant immigration or residence rules.
- Student Eligibility: A full-time student does not qualify under one of the permitted exceptions.
- Household Circumstances: Income or other information means the calculated entitlement is zero.
An application can also be stopped if required claimant commitments are not accepted.
Applicants should read their decision notice carefully to understand the precise reason for refusal or closure.
How To Request A Mandatory Reconsideration?
If a claimant believes the DWP has made an incorrect decision about their Universal Credit entitlement, they can usually request a mandatory reconsideration.
This allows the DWP to review its original decision and consider relevant evidence.
The process normally involves:
- Reviewing The Decision Notice: Identify why the application was refused.
- Requesting Reconsideration: Contact the DWP through the Universal Credit journal, telephone or another accepted method.
- Providing Supporting Evidence: Explain which part of the decision is incorrect and submit relevant information.
- Receiving A Revised Decision: The DWP issues a mandatory reconsideration notice explaining the outcome.
Claimants normally need to request mandatory reconsideration within one month of the date on the decision letter.
Late requests may be accepted where there is a good reason for the delay.
If the claimant still disagrees after mandatory reconsideration, they may be able to appeal to an independent tribunal.
Official guidance is available at https://www.gov.uk/mandatory-reconsideration/how-to-ask-for-mandatory-reconsideration.
Can You Get Money Before Your First Universal Credit Payment?
Applicants who are struggling financially while waiting for their first payment may be able to request a Universal Credit advance.
This is an interest-free advance against expected entitlement, rather than an additional benefit payment.
It can help cover essential costs such as food, rent and household bills while the normal payment schedule is being established.
How To Apply For A Universal Credit Advance?
Claimants can request a first-payment advance by:
- Using Their Universal Credit Journal: Contact the DWP through their online account.
- Speaking To A Work Coach: Ask about an advance during an appointment or through the jobcentre.
- Calling the Universal Credit Helpline: Request assistance with the application process.
Applicants usually need to explain why they need the money, verify their identity and provide relevant financial information.
The DWP normally tells applicants whether they can receive an advance on the same day they apply.
The time taken for the money to reach an account may vary. The Universal Credit advance payment bank transfer process is therefore important for claimants who need funds urgently.
How Much Can You Receive And When Must You Repay It?
The maximum first-payment advance is normally equal to the claimant’s estimated first Universal Credit payment.
For example, someone expecting £600 in Universal Credit may be able to request an advance of up to £600, subject to the DWP’s assessment.
Claimants can request a smaller amount if they only need help with certain expenses.
First-payment advances must usually be repaid within 24 months, with repayments deducted from future Universal Credit payments.
If someone receives a £480 advance and repays it evenly over 24 months, the repayment would be approximately £20 per month.
Applicants experiencing financial difficulty may request a repayment delay of up to three months, subject to the applicable rules.
It is important to remember that receiving an advance does not create an entitlement to Universal Credit if the underlying claim is unsuccessful. Any outstanding advance remains repayable.
The normal five-week payment schedule is important, but it should not be confused with a guaranteed deadline for approval.
Completing verification, responding to DWP messages and understanding the reasons for any delay can help applicants manage their claim and obtain a clear decision.
Frequently Asked Questions
Can Universal Credit Be Approved Before Five Weeks?
Yes. Eligibility checks can be completed before the first payment date. However, the first payment normally follows the standard assessment and payment schedule.
How Long Does Universal Credit Take After Identity Verification?
There is no fixed timeframe. The DWP may still need to check income, housing details, claimant commitments or other eligibility information.
Why Is My Universal Credit Claim Still Being Processed?
The DWP may be waiting for documents, identity checks, appointment outcomes or additional information. Check your journal and to-do list for outstanding requests.
Can Universal Credit Take Longer Than Five Weeks?
Yes. Complicated eligibility checks or missing information can delay a decision or payment beyond the usual five-week timeframe.
What Happens If I Miss My Universal Credit Appointment?
Contact Universal Credit immediately and explain why you missed it. Depending on the circumstances, a missed appointment could delay progress, affect your claim or lead to a sanction.
Can I Receive Universal Credit Without A Bank Account?
Yes, alternative payment arrangements may be possible. Contact the Universal Credit helpline or a jobcentre if you cannot open a suitable account.
Does Universal Credit Take Longer If I Have Recently Moved To The UK?
It can. Additional residence or immigration-status checks may be necessary before the DWP can establish whether you qualify.