How To Apply For Universal Credit In 2026: Complete Step-by-Step Guide
Applying for Universal Credit in 2026 is mainly an online process, but a successful claim involves much more than simply completing a form. Claimants need to provide accurate information about their household, income, savings, housing costs and personal circumstances.
They may also need to verify their identity, attend an appointment and agree to a claimant commitment.
Universal Credit now supports millions of people across Great Britain, including people who are unemployed, working on a low income, caring for someone or unable to work because of a health condition.
Knowing when to apply, what information to prepare and what happens after submission can reduce the risk of delays or incorrect payments.
Anyone ready to make a claim can apply for Universal Credit through the official GOV.UK service. Applicants need to create an online account and normally submit their claim within 28 days of creating it.
How Has Applying For Universal Credit Changed Over The Years?
Universal Credit was introduced in 2013 as part of a major change to the benefits system. It gradually replaced six means-tested legacy benefits and tax credits with one monthly payment.
In the earlier years, Universal Credit was introduced gradually by area and claimant group. The system has since developed into a largely digital service where most people create an online account, complete their claim online and manage ongoing requirements through that account.
By 2026, the Universal Credit account has become central to the process. Claimants use it to complete their to-do list, read journal messages, report changes, check payments and communicate about their claim.
Identity checking has also changed. Current DWP guidance says Universal Credit no longer uses Government Gateway or GOV.UK Verify for online identity verification.
Identity can instead be established through online verification, documentary evidence, face-to-face appointments or biographical interviews.
The wider move from legacy benefits has also contributed to a substantial increase in the Universal Credit caseload.
How Does Universal Credit In 2026 Compare With The Previous Benefits System?
Universal Credit was designed to bring several forms of means-tested support into a single system.
It replaced Income Support, income-based Jobseeker’s Allowance, income-related Employment and Support Allowance, Housing Benefit for most working-age claimants, Working Tax Credit and Child Tax Credit.
Instead of dealing separately with several benefit systems, most Universal Credit claimants now manage one claim through a single online account.
There are still important differences between Universal Credit and the previous system.
Universal Credit is normally assessed monthly, household circumstances are considered together for couples and payments can change as earnings or circumstances change.
The digital account also creates ongoing responsibilities. Claimants may need to check messages, complete tasks and report changes rather than treating the application as a one-off process.
How Many People Depend On Universal Credit In 2026?
Universal Credit has become one of the largest forms of working-age financial support in Great Britain.
Official DWP statistics published in August 2026 show that 8.4 million people were on Universal Credit in May 2026, the highest number recorded since the benefit was introduced. This had increased from 7.7 million in May 2025.
There were also 7.2 million Universal Credit households in May 2026. Around 6.7 million, or 94%, were recorded as having a Universal Credit payment.
Households with children represented 44% of households receiving a payment. The figures also show that Universal Credit is not limited to people who have no employment.
Earlier 2026 statistics recorded millions of Universal Credit claimants in employment.
Part of the recent increase reflects the continued movement of people from older benefits onto Universal Credit rather than entirely new dependence on the welfare system.
DWP reported that Move to Universal Credit claimants accounted for 73.2% of the increase between May 2025 and May 2026.
How Important Is Universal Credit To Household Income In 2026?
For many households, Universal Credit contributes towards essential living costs such as food, housing, childcare and other everyday expenses.
The basic amount begins with a standard allowance, although the final award can include additional elements depending on circumstances.
For the 2026 to 2027 benefit year, monthly standard allowances are:
Claimant Circumstances Monthly Standard Allowance
Single And Under 25 £338.58
Single And Aged 25 Or Over £424.90
Couple Both Under 25 £528.34
Couple Where One Or Both Are 25 Or Over £666.97
Additional amounts can potentially be included for children, childcare, caring responsibilities, housing costs and qualifying health conditions.
Earnings, savings, other income, deductions and the Benefit Cap can affect the amount actually paid.
The importance of Universal Credit is also illustrated by deductions. Around 3.3 million households, representing 47% of Universal Credit households, had one or more deductions from their entitlement in May 2026.
This means the headline maximum award is not necessarily the amount a household receives into its bank account.
Who Can Apply For Universal Credit In 2026?
Universal Credit is generally available to working-age people who need help with living costs. A claimant might be unemployed, working on a low income, self-employed or unable to work.
In general, a person normally needs to live in the UK, be below State Pension age and have no more than £16,000 in savings and other relevant capital.
Savings between £6,000 and £16,000 can reduce Universal Credit. The upper capital limit remains £16,000 for 2026 to 2027.
Special rules can apply to students, people aged 16 or 17, mixed-age couples and people whose immigration status affects access to public funds.
Someone who has worked during the previous two or three years may also need to check whether New Style Jobseeker’s Allowance or New Style Employment and Support Allowance could apply alongside or instead of part of their Universal Credit support.
When Should You Apply For Universal Credit?
Usually, applying as soon as someone becomes eligible means the first payment can arrive sooner. However, timing can matter significantly where employment has recently ended.
If someone leaves a job and expects final wages or holiday pay, Citizens Advice recommends considering waiting until the day after those payments arrive before starting a new claim.
Money received from employment after the claim begins may fall within the assessment period and reduce the first Universal Credit payment.
Redundancy payments are treated differently from normal earnings, although a redundancy payment can affect Universal Credit if it increases savings or capital.
The claim date is important because the first monthly assessment period generally begins when the Universal Credit claim is made.
Claimants should therefore consider both the urgency of financial support and any wages that are still due.
What Do You Need Before Applying For Universal Credit?
Preparing information before creating the claim can make the application easier and reduce mistakes.
Claimants may need:
- National Insurance Details: Have your National Insurance number available where possible. A person who does not yet have one may still be able to begin a claim.
- Contact Details: Prepare an email address and telephone number for the online account and communications.
- Housing Information: Have details of rent, tenancy arrangements, service charges, landlord information and housing circumstances.
- Income Details: Prepare recent earnings information, payslips and details of pensions or other income.
- Savings And Capital: Include bank balances, savings, investments, shares and relevant property.
- Bank Details: Have details of the account into which Universal Credit will normally be paid.
- Childcare Details: Prepare information about childcare providers, payments and evidence of costs if claiming childcare support.
- Health Information: Give accurate details of illnesses, disabilities or ongoing health conditions that affect work.
- Other Benefits: Have information about other benefits or financial support currently being received.
- Partner Details: Couples should prepare information about both people’s income, savings and circumstances.
Accurate information is particularly important because incorrect housing, childcare, earnings or capital information can affect the award.
How To Apply For Universal Credit Online Step By Step?
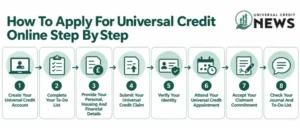
Step 1: Create Your Universal Credit Account
Most Universal Credit claims begin online.
You need an online account before submitting the application. The account becomes the main place for managing the claim after it has been submitted.
A claim must normally be submitted within 28 days of creating the account. Otherwise, the claimant may need to start again.
Step 2: Complete Your To-Do List
The account contains a to-do list covering different parts of the application.
Questions can include nationality, housing, employment, earnings, savings, education, health, children, caring responsibilities and bank information.
The entire application does not necessarily have to be completed in one sitting. Saved information can be returned to later, but claimants should complete outstanding sections promptly.
Step 3: Provide Your Personal, Housing And Financial Details
Enter information carefully and use supporting documents where possible.
Housing details should match the tenancy or other evidence. Income and savings should reflect the claimant’s actual financial position.
For childcare support, evidence may be required showing the provider, payment and dates covered.
Step 4: Submit Your Universal Credit Claim
Once all required sections have been completed, the claimant can submit the claim.
This step is particularly important because the claim does not formally begin simply because an account has been created. The application needs to be submitted.
The submission date usually becomes relevant to the first assessment period and first payment timetable.
Step 5: Verify Your Identity
Universal Credit claimants must establish their identity.
Current 2026 guidance allows identity to be verified through online identity checks, face-to-face appointments, documentary evidence or biographical interviews.
For online verification, current guidance lists items including a valid UK passport, UK driving licence, recent Self Assessment information and certain credit records.
Payslips and P60s are no longer accepted as online identity verification evidence.
Step 6: Attend Your Universal Credit Appointment
After submitting the claim, the claimant will be told whether an appointment is required and how it will take place.
Current GOV.UK guidance says the Jobcentre Plus interview should be arranged within 10 working days after submitting the claim.
The appointment can be important for checking evidence, discussing circumstances and establishing what the claimant is expected to do.
Step 7: Accept Your Claimant Commitment
Many claimants need to accept a claimant commitment.
This sets out responsibilities connected with receiving Universal Credit.
Requirements depend on individual circumstances and might include looking for work, increasing earnings, attending appointments or taking agreed steps towards employment.
Someone with caring responsibilities, a health condition or other relevant circumstances may have different requirements.
Step 8: Check Your Journal And To-Do List
Submitting the claim does not mean there is nothing else to do.
The journal and to-do list should be checked regularly for requests from DWP.
Missing a request for evidence or an appointment can delay the claim and, once a claim is active, failing to meet certain agreed requirements without good reason can affect payments.
What Happens After You Submit A Universal Credit Claim?
After submission, DWP begins assessing the claimant’s circumstances.
The online account may show additional tasks. Claimants can receive requests to verify their identity, provide documents, confirm housing costs or attend an interview.
The Universal Credit journal becomes particularly important at this stage. It can be used for communication about the claim and for keeping track of actions that need to be completed.
Claimants should respond promptly when information is requested.
A work capability assessment may also be required where a health condition or disability affects a person’s ability to work. DWP should tell the claimant if an assessment is needed.
How Long Does Universal Credit Take After Applying?
The first Universal Credit payment is normally made five weeks after the claim begins.
The first month is generally the assessment period. DWP looks at the claimant’s circumstances and relevant income during this period. Payment usually follows seven days after the assessment period ends.
For example, someone whose assessment period starts on 10 October would normally have the monthly assessment period running to 9 November, with payment following around a week later.
The online account should show the amount due before payment.
Delays can occur if DWP is waiting for identity verification, housing evidence, financial information, appointments or other required details.
Can You Get An Advance Before Your First Universal Credit Payment?
Someone who cannot manage living costs while waiting for the first payment may be able to request an advance.
A first-payment advance is effectively an early payment of Universal Credit that must later be repaid.
The amount available depends on the claimant’s estimated entitlement and circumstances. DWP may ask why the advance is needed and may require information about available savings or other money.
Repayment is normally taken from future Universal Credit payments.
Claimants should therefore consider the effect of repayments on their later monthly income before requesting the maximum available amount.
How Do Couples Apply For Universal Credit Together?
Couples who live together will normally need to make a joint Universal Credit claim.
Each partner creates their own Universal Credit account. One partner receives a linking code, which the other uses to connect the two accounts. Once linked, the application is treated as a joint claim.
Both partners can access their accounts individually.
DWP generally considers the household’s combined income, savings and circumstances when calculating Universal Credit.
Even where one partner is not personally eligible, information about both partners can still be relevant to the calculation.
Can You Apply Without A Bank Account Or Permanent Address?
Not having a permanent home does not automatically prevent someone from making a Universal Credit claim.
People who are homeless, sleeping rough, living in temporary accommodation or sofa surfing can still potentially claim.
Where someone does not have an address, arrangements can be made using an appropriate contact address or Jobcentre details depending on the circumstances.
Banking can require more planning. Universal Credit is normally paid into a bank, building society or credit union account.
Citizens Advice guidance explains that in some circumstances a claimant may be able to use a trusted friend or family member’s account for the first payment with permission and then arrange their own account.
Where opening an account is genuinely not possible, alternative payment arrangements such as the Payment Exception Service may need to be discussed.
What Happens If You Receive A Universal Credit Migration Notice?
A Migration Notice tells someone receiving certain older benefits that they need to claim Universal Credit.
The claimant should check the specific deadline shown in the Migration Notice rather than assuming that every person receives exactly the same amount of time.
Moving from legacy benefits to Universal Credit can have significant financial consequences. Once a Universal Credit claim is made, benefits replaced by Universal Credit normally cannot simply be restarted.
Some people moving through the managed migration process may qualify for transitional protection where the required conditions are met.
Anyone unsure about whether or when to submit a Migration Notice claim should check the notice carefully and seek benefits advice before missing the stated deadline.
Can Universal Credit Be Backdated?
Universal Credit normally starts from the date the claim is submitted rather than automatically covering an earlier period.
In limited circumstances, a claim can potentially be treated as having started earlier. Backdating is generally restricted and a claimant normally needs to explain why they could not reasonably have claimed on time.
Situations involving serious illness, disability or certain problems with the claiming service may be relevant depending on the facts.
A claimant requesting backdating should explain the circumstances clearly and provide supporting evidence where available.
Because Universal Credit backdating rules are limited, people should not delay a claim on the assumption that payment can simply be recovered later.
How Do You Reapply For Universal Credit?
The process depends partly on how long it has been since the previous Universal Credit payment.
Citizens Advice guidance says that where it has been less than six months, a claimant can normally use their previous Universal Credit account to reapply. This can be quicker than making a completely new application.
Where it has been more than six months, a new claim normally needs to be started.
People returning to Universal Credit after leaving employment should also consider the timing of final wages. If final employment income arrives after a new claim begins, it can affect the first Universal Credit payment.
Eligibility should still be checked again because circumstances may have changed since the previous claim.
What Should You Do If Your Universal Credit Claim Is Delayed Or Refused?
If a claim appears to be delayed, first check the Universal Credit account carefully.
Look for outstanding tasks, journal messages, appointments, identity checks or evidence requests. Housing verification and missing financial information can also hold up parts of a claim.
If everything appears complete but progress has stopped, contact Universal Credit through the appropriate account or support route and ask what remains outstanding.
If DWP makes a decision that the claimant believes is incorrect, the decision can normally be challenged through mandatory reconsideration.
A mandatory reconsideration normally needs to be requested within one month of the date of the decision. A late request may sometimes be accepted where there is a good reason.
The claimant should explain which part of the decision they believe is wrong, why it is wrong and provide relevant evidence.
Where Can You Get Help With A Universal Credit Application?
People who cannot manage the application alone can get support.
Universal Credit support may be available through Jobcentre Plus and the Universal Credit helpline. Citizens Advice also provides Help to Claim support for people making a Universal Credit claim.
People who cannot access the internet may be able to use facilities at a Jobcentre, council office or local library.
Extra support can be particularly valuable for people with disabilities, language barriers, limited digital skills, complicated immigration circumstances or difficulty providing evidence.
Conclusion
Applying for Universal Credit in 2026 is primarily digital, but getting the application right requires preparation. Claimants need to consider eligibility, claim timing, household circumstances, income, savings and housing details before submitting the application.
The process does not finish when the online claim is sent. Identity verification, appointments, the claimant commitment, journal messages and outstanding to-do list tasks can all affect progress.
With 8.4 million people receiving Universal Credit in May 2026, the benefit now plays a major role in supporting households across Great Britain.
Understanding each stage of the process can help claimants avoid preventable delays and receive the correct support based on their circumstances.
Frequently Asked Questions
Can I Apply For Universal Credit Before My Job Ends?
A person can potentially qualify for Universal Credit while working if their income and circumstances meet the rules.
However, people who are leaving employment should consider when final wages or holiday pay will arrive because earnings received during the first assessment period can affect the first payment.
Can I Claim Universal Credit If I Am Self-Employed?
Yes. Self-employed people can claim Universal Credit if they satisfy the eligibility requirements.
They may need to report business income and expenses regularly, and special rules such as the Minimum Income Floor can apply depending on their circumstances.
Can I Apply For Universal Credit Without A National Insurance Number?
Not having a National Insurance number available does not necessarily prevent someone from starting a Universal Credit claim.
Additional identity and personal information may be required so DWP can establish the claimant’s details.
Can I Save My Universal Credit Application And Finish It Later?
Yes. Parts of the online application can normally be completed at different times.
Claimants should save their information and return promptly because the claim needs to be submitted within 28 days of creating the Universal Credit account.
What Happens If I Make A Mistake On My Universal Credit Application?
Correct the information as soon as possible. Depending on when the mistake is discovered, this may involve updating the online account, using the journal or contacting Universal Credit.
Incorrect information can lead to delayed, reduced or excessive payments, and overpayments may need to be repaid.