What to Check Before Choosing Used Car Finance?
Financing a used car can help spread the cost of a vehicle over time, making it easier to budget for a purchase without paying the full amount at once. However, it is still a significant financial commitment.
Before applying, it is worth taking time to understand the vehicle, the agreement, and the total cost.
A careful approach can help you choose a car that is practical for your lifestyle and a finance arrangement that remains manageable throughout the term.
Choose the Car Before Focusing on the Payment
It can be tempting to begin with the monthly payment, but the car itself should come first.
A lower payment is not always good value if the vehicle has high running costs, does not suit your needs, or requires expensive repairs.
Think about what you need from the car on a daily basis. Consider passenger space, boot capacity, fuel type, typical mileage, parking needs, and the type of journeys you make.
For example, a small hatchback may suit short urban journeys and lower running costs, while a larger estate or SUV may be more suitable for a family, regular motorway travel, or carrying equipment.
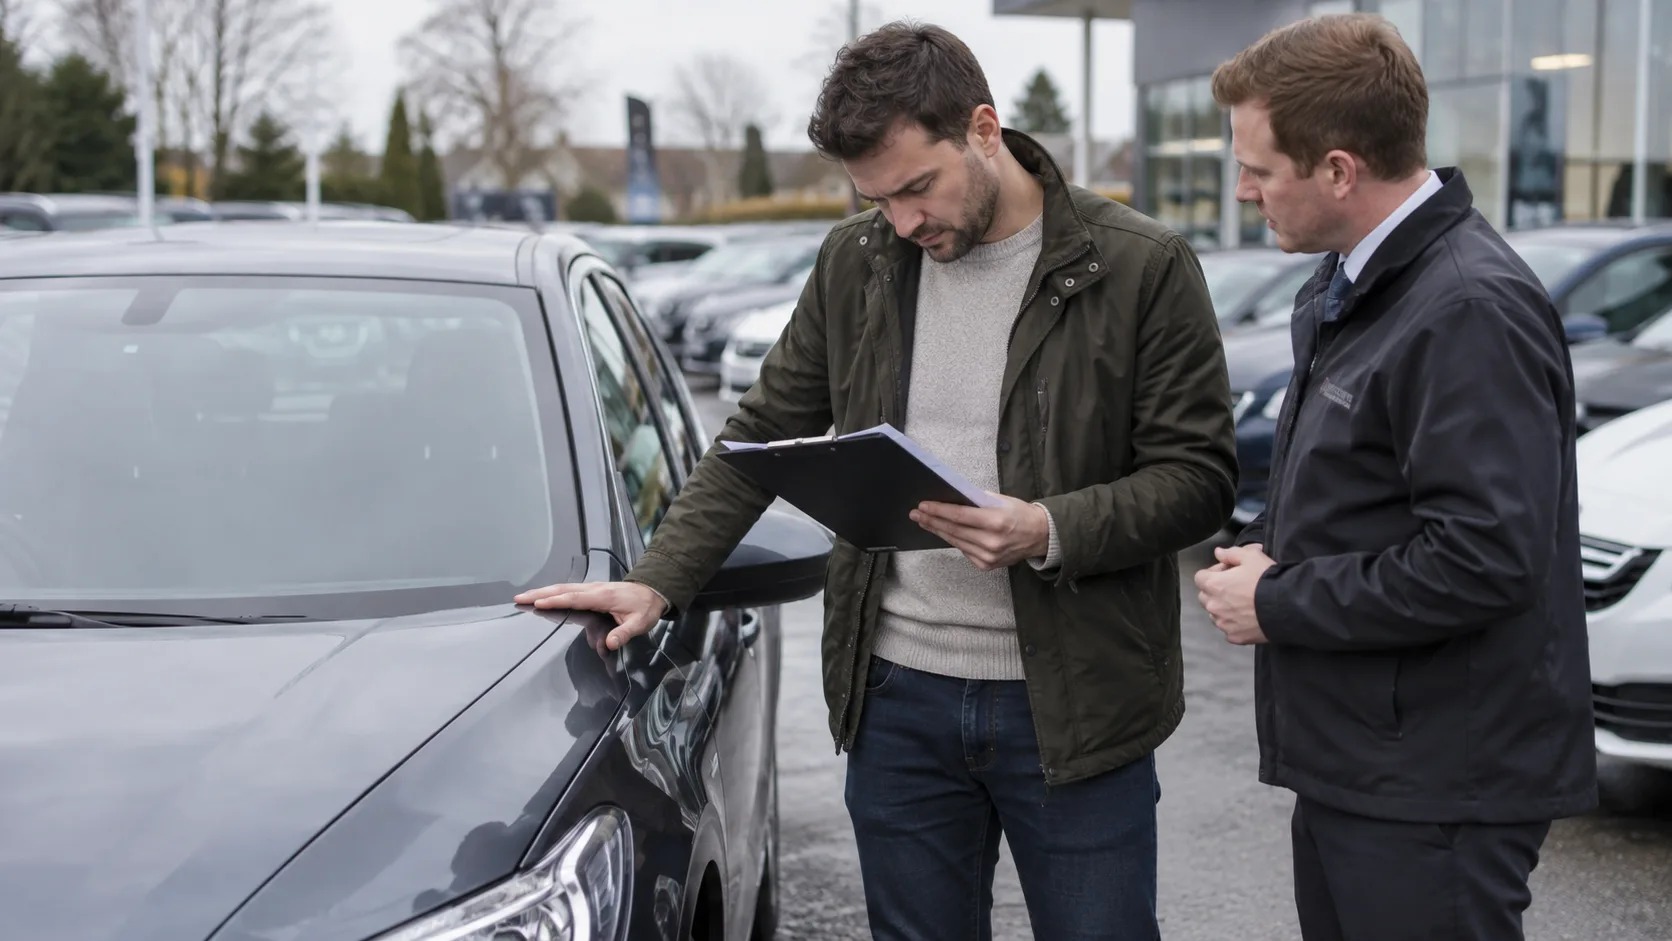
When looking at Used Cars on Finance, compare more than the model and appearance. Check the vehicle’s service history, MOT history, mileage, condition, and likely insurance group.
Work Out What You Can Afford
Before entering a finance agreement, review your regular income and essential outgoings.
Your car payment should fit comfortably within your budget after accounting for housing, food, utilities, childcare, existing credit commitments, and other necessary costs.
Remember to include the ongoing costs of owning a vehicle, such as:
- Insurance
- Fuel or charging
- Servicing and repairs
- MOT costs
- Vehicle tax
- Parking and tolls
- Tyres and replacement parts
It is also sensible to leave some room in your budget for unexpected expenses. A finance agreement may last several years, so choose a payment you can afford in both the short and longer term.
Compare the Total Amount Repayable
Monthly payments are important, but they do not show the full picture. A lower monthly payment may be achieved by extending the agreement term, which can mean paying more interest overall.
Before signing, check:
- The cash price of the vehicle
- The deposit, if required
- The amount borrowed
- The interest rate and APR
- The agreement length
- The total amount repayable
- Any fees or charges
- The consequences of late or missed payments
Ask the provider to explain anything you do not understand. You should never feel pressured to agree to finance before you have had time to read the terms.
Understand the Type of Agreement
Different finance products work in different ways. The agreement should suit both your budget and your plans for the car.
Hire Purchase
With hire purchase, you usually make regular payments over an agreed term. After making all required payments and any relevant fee, ownership of the vehicle normally transfers to you.
This can be suitable for buyers who want to own the car at the end of the agreement.
Personal Contract Purchase
Personal contract purchase agreements can have lower monthly payments because a final payment is usually left until the end of the term.
At that point, you may have options to return the vehicle, make the final payment to keep it, or use any available equity towards another car.
With this type of agreement, check any mileage limit, vehicle condition requirements, and the amount of the optional final payment. These should be clear before you commit.
Other Borrowing Options
Some buyers may use a personal loan or another form of borrowing. The right option will depend on the available terms, your circumstances, and how you want ownership to work.
Researching finance for used cars can help you compare your options, but the offer you receive will depend on affordability checks and your individual circumstances.
Check the Vehicle and Paperwork
A used car should be inspected carefully before purchase. Arrange a test drive where possible and pay attention to how the car starts, brakes, steers, and handles.
Look for signs of wear, damage, or warning lights. Ask to see service records and relevant vehicle documentation. A vehicle history check can provide additional information about matters such as outstanding finance or previous insurance records.
If you are unsure about the condition of the car, consider arranging an independent inspection. The cost may be worthwhile if it helps you avoid an unsuitable purchase.
Be Honest During the Application
Finance providers will consider factors such as income, outgoings, and credit history when assessing an application. Give accurate information and do not take on a payment that feels difficult to maintain.
Approval is not a reason to ignore affordability. A lender or broker may provide options, but you should still decide whether the agreement is right for you.
If your financial circumstances change after taking out finance, contact the provider as soon as possible. Dealing with a problem early is usually better than waiting until payments have been missed.
Conclusion
Used car finance can be a useful way to spread the cost of a vehicle, but it is important to look beyond the monthly payment.
By choosing a suitable car, reviewing the total cost, understanding the agreement, and assessing affordability honestly, you can make a more informed decision.
FAQ
What should I compare when choosing used car finance?
Compare the vehicle price, deposit, monthly payment, APR, agreement term, total amount repayable, fees, and any end-of-agreement conditions.
Is a longer finance term always better?
Not necessarily. A longer term may reduce monthly payments, but it can increase the total amount paid in interest. Check the full cost before deciding.
Can I finance any used car?
Finance availability can depend on the vehicle’s age, value, condition, and the provider’s criteria. Check the requirements before committing to a car.
What happens if I miss a car finance payment?
Late or missed payments can lead to additional charges and may affect your credit record. Contact the lender promptly if you are struggling to pay.