Can I Claim Jobseeker’s Allowance If I Have Savings in 2026?
Yes, you can claim New Style Jobseeker’s Allowance (JSA) even if you have savings. There is no savings or capital limit for New Style JSA. This means having £6,000, £16,000 or even more than £20,000 in savings does not automatically prevent you from qualifying.
The same applies to savings held by your partner. New Style JSA is mainly based on your recent employment history and whether you have paid enough Class 1 National Insurance contributions. You must also satisfy rules relating to your age, working hours, availability for work and location in Great Britain.
This is different from older income-based JSA and Universal Credit, where savings can affect entitlement. Income-based JSA is now closed to new applications, so people making a new claim in 2026 normally need to consider New Style JSA, Universal Credit or potentially both.
Is There a Savings Limit for New Style JSA?
There is no specific savings limit for New Style JSA. A claimant can potentially qualify whether they have £1,000, £10,000, £16,000 or considerably more saved.
This is because New Style JSA is a contributory benefit rather than a means-tested benefit.
Eligibility depends primarily on whether the claimant has worked as an employee and paid sufficient Class 1 National Insurance contributions.
For example:
Amount in Savings Can Savings Prevent New Style JSA?
£3,000 No
£6,000 No
£10,000 No
£16,000 No
£20,000 No
More Than £20,000 No
Savings alone do not guarantee that someone can receive JSA. They must still meet the other eligibility conditions.
The £16,000 figure often causes confusion because it is associated with Universal Credit and older means-tested benefits, rather than New Style JSA.
Savings and income are also different. Although capital itself does not reduce New Style JSA, earnings from work and some pension income can affect how much a claimant receives.
Can You Still Claim Income-Based JSA in 2026?
New claims for income-based Jobseeker’s Allowance are no longer available. People who need means-tested financial support are generally directed towards Universal Credit instead.
This distinction is important because older information about JSA often refers to the following capital rules:
- £6,000 Or Less: Capital generally did not reduce income-based JSA
- Between £6,000 And £16,000: Capital could reduce entitlement
- More Than £16,000: A claimant would normally be unable to receive income-based JSA
These limits should not be applied to a new New Style JSA claim.
Someone with £20,000 in savings, for example, could potentially qualify for New Style JSA if they satisfy the National Insurance and other eligibility conditions.
The same person would normally face a very different capital assessment when applying for Universal Credit.
What Can Cause My JSA to Stop or Be Cancelled?
Savings are not normally what causes New Style JSA to end. A claim can instead be affected by changes in employment, eligibility or whether the claimant continues meeting their responsibilities.
Starting Work or Working Too Many Hours
New Style JSA is intended for people who are unemployed or working only a limited number of hours.
A claimant cannot usually receive New Style JSA if they work 16 hours or more per week. Earnings from work can also reduce the amount of JSA received even where the person works fewer than 16 hours.
Claimants therefore need to report changes such as starting a new job or changes to their income.
Failing to Follow Your Claimant Commitment
When someone claims JSA, they normally agree a Claimant Commitment with their work coach.
It can include activities such as:
- Looking For Suitable Jobs
- Applying For Vacancies
- Preparing Or Updating A CV
- Registering With Recruitment Agencies
- Attending Employment Support Activities
- Spending An Agreed Amount Of Time Looking For Work
Failing to follow these requirements without a good reason can result in JSA being reduced or stopped.
Missing Jobcentre Appointments Without Good Reason
Claimants are normally expected to attend regular appointments with their work coach.
Missing an appointment without an accepted reason can result in a sanction.
A claimant may also face sanctions for refusing suitable work, failing to apply for a job they were instructed to apply for or failing to attend required training.
Anyone who cannot attend an appointment should contact Jobcentre Plus as soon as possible and explain the circumstances.
No Longer Being Available or Looking for Work
New Style JSA is linked to actively seeking employment.
Payments can be affected if a claimant is no longer available to start work, repeatedly refuses appropriate opportunities or does not complete agreed work-search activities.
Leaving a job or training programme without a good reason can also lead to a sanction rather than automatically making someone permanently ineligible for JSA.
How Has Jobseeker’s Allowance Changed Over the Years?
The benefit available to unemployed people has changed considerably over the past three decades.
The most significant change has been the gradual movement of means-tested unemployment support from JSA into Universal Credit.
1996: Jobseeker’s Allowance Is Introduced
Jobseeker’s Allowance was introduced in October 1996.
It brought together elements of the previous unemployment benefit system and means-tested support for unemployed people.
JSA developed into two main forms.
- Contribution-based JSA depended largely on National Insurance contributions.
- Income-based JSA was means-tested and considered factors including income, savings and household circumstances.
This distinction is the main reason older JSA guidance frequently discusses £6,000 and £16,000 savings thresholds.
2013: Universal Credit Begins Replacing Income-Based JSA
Universal Credit began being introduced in 2013 as part of a major restructuring of working-age benefits.
It gradually replaced several means-tested benefits, including income-based JSA.
As Universal Credit expanded across the country, fewer people remained on income-based JSA.
Official statistics show that the JSA caseload fell substantially between August 2012 and March 2020, with the rollout of Universal Credit being a major reason for the decline.
2021: New Claims Shift to New Style JSA
As the transition towards Universal Credit progressed, traditional income-based JSA stopped being available for new claims.
New claimants seeking contribution-based unemployment support instead use New Style JSA.
People requiring additional means-tested support may be able to claim Universal Credit alongside or instead of New Style JSA, depending on their circumstances.
2026: How JSA Works Today?
By 2026, JSA has a much narrower role than it had when first introduced.
The scheme is now open to contributory claims through New Style JSA. Income-based JSA has largely been replaced by Universal Credit.
This is why savings no longer determine whether a new claimant can receive JSA. Instead, National Insurance contributions and other eligibility requirements are central to New Style JSA.
How Many People Claim JSA and How Has This Changed Over Time?
Jobseeker’s Allowance once supported a much larger number of unemployed people, but its role has reduced significantly as Universal Credit has expanded.
Official DWP figures show that 77,000 people were claiming JSA in March 2026.
Claim numbers fell substantially between August 2012 and March 2020 as Universal Credit progressively replaced income-based JSA.
The COVID-19 pandemic temporarily changed this trend. JSA claims rose substantially as employment conditions deteriorated and more people sought financial support.
Since then, the number has fallen again. By March 2026, JSA claims were below their pre-pandemic level.
This does not necessarily mean fewer people require unemployment-related support overall. Many people who might previously have claimed income-based JSA are now supported through Universal Credit.
The decline therefore reflects a major change in the benefits system rather than simply a reduction in financial need among unemployed households.
What National Insurance Contributions Do I Need for New Style JSA?
New Style JSA is based largely on National Insurance contributions.
To qualify, a person generally needs to have:
- Worked As An Employee
- Paid Sufficient Class 1 National Insurance Contributions
- Usually Built Up Contributions During The Relevant Recent Tax Years
- Reached At Least Age 18
- Remained Below State Pension Age
- Been In Great Britain
- Worked Fewer Than 16 Hours Per Week
Someone who was self-employed and only paid Class 2 National Insurance contributions will not normally qualify, although specific exceptions apply to certain groups such as share fishermen and volunteer development workers.
Having substantial savings cannot compensate for an insufficient contribution record.
This means somebody with no savings could be refused New Style JSA because they do not satisfy the National Insurance requirements, while another person with £30,000 saved could qualify because their contribution history meets the rules.
Does Pension Income, Inheritance or Redundancy Pay Affect JSA?
Different forms of money need to be distinguished from ordinary earnings.
Inheritance: Receiving an inheritance can increase a person’s savings, but savings themselves do not create a capital limit for New Style JSA.
However, an inheritance could affect means-tested benefits such as Universal Credit.
Redundancy Payment: A lump-sum redundancy payment may substantially increase someone’s savings, but the resulting capital does not automatically prevent them claiming New Style JSA.
Pension Income: Pension income is different because certain occupational or personal pension payments can affect the amount of contributory JSA received.
Claimants receiving money from pensions, employment or other sources should therefore report the relevant change rather than assuming that every type of money is treated as savings.
What Is the Difference Between New Style JSA and Universal Credit?
New Style JSA and Universal Credit can both provide support to people who are unemployed, but the eligibility systems are different.
Rule New Style JSA Universal Credit
Based On NI Contributions Yes No
Savings Are Means-Tested No Yes
Partner’s Savings Affect Claim No Yes
Partner’s Income Generally Considered No Yes
£16,000 Capital Limit No Normally Yes
Housing Costs Can Be Included No Yes
Maximum Standard Claim Period 182 Days No Equivalent Fixed 182-Day Limit
A person may sometimes receive New Style JSA and Universal Credit at the same time.
However, New Style JSA counts as income for Universal Credit and therefore reduces the Universal Credit award.
The interaction between the two benefits is particularly important for someone with savings.
A claimant might qualify for New Style JSA regardless of substantial savings while being unable to receive Universal Credit because of the amount of household capital they hold.
How Much Is New Style JSA in 2026?
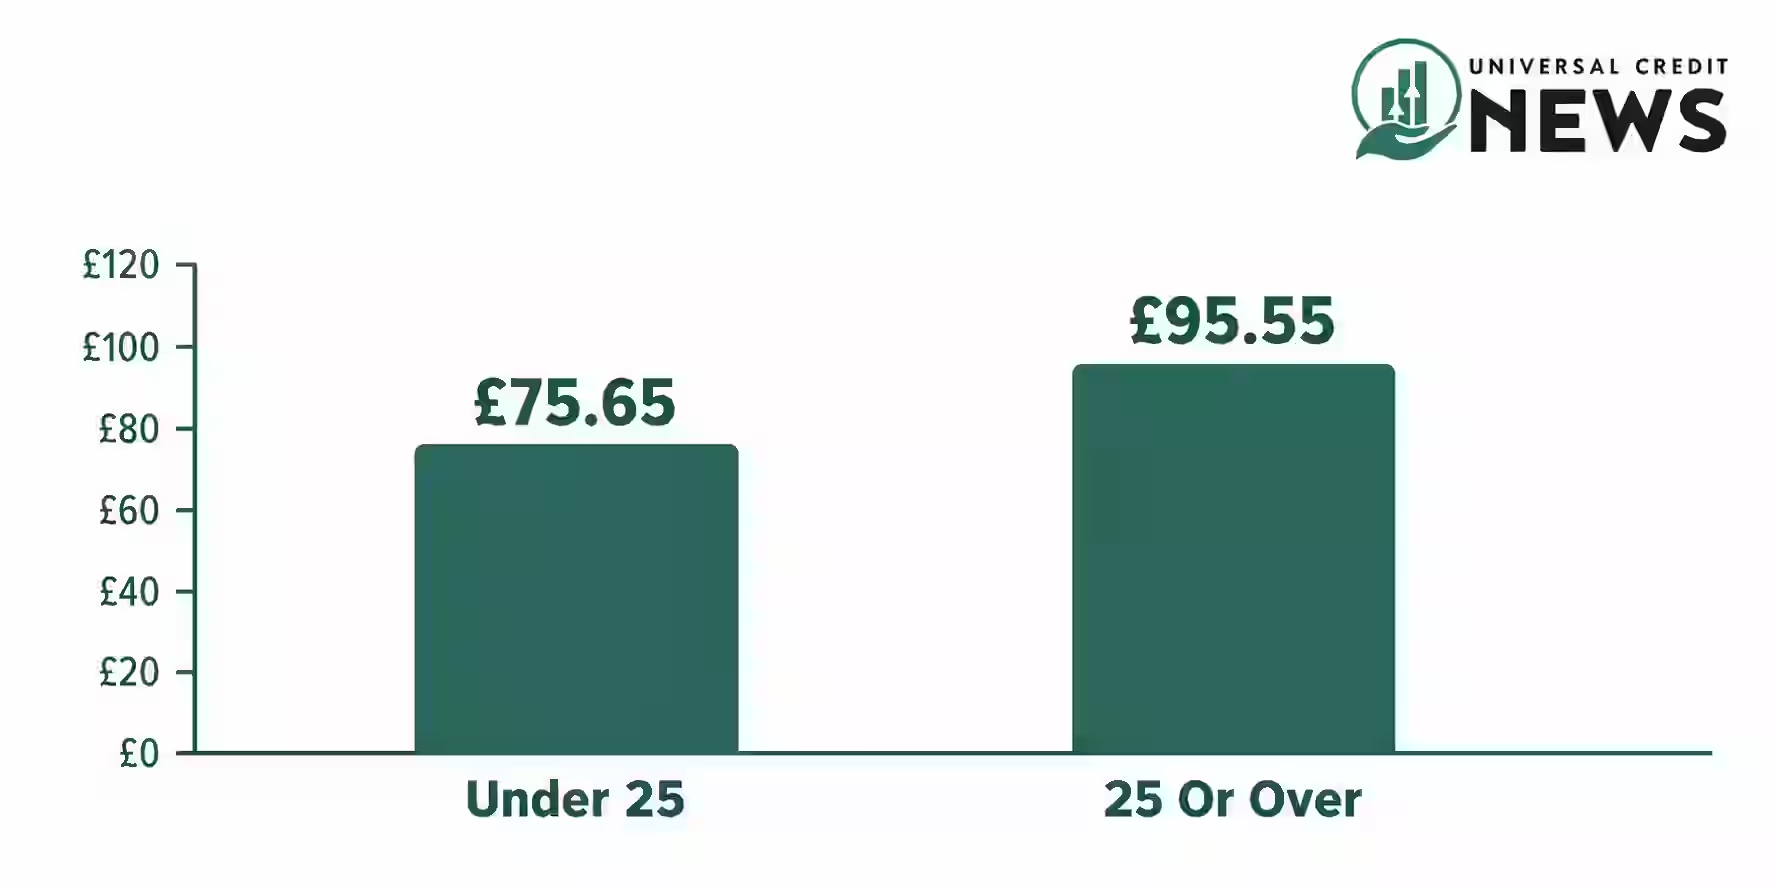
For the 2026/27 benefit year, the maximum weekly New Style JSA rates are:
Age Maximum Weekly JSA
Under 25 £75.65
25 Or Over £95.55
These rates took effect as part of the 2026/27 benefit uprating.
The amount actually received can depend on an individual’s circumstances and other income that affects the award.
JSA is normally paid into a bank, building society or credit union account. After the first payment, payments are usually made every two weeks.
How Long Can I Receive New Style JSA?
New Style JSA can normally be paid for up to 182 days, which is approximately six months.
The 182-day limit applies even if the claimant still has no job when the period ends.
Savings do not extend or shorten this maximum period.
For example, someone with £20,000 in savings who qualifies for New Style JSA does not receive a shorter entitlement simply because they have more capital.
Claimants are normally informed when their payments are approaching the end of the 182-day period. If their circumstances have not otherwise changed, payments will stop after that point.
They can then discuss other employment and financial support options with their work coach. Depending on their household circumstances and savings, Universal Credit may be one potential option.
What Happens If My JSA Claim Is Refused, Stopped or Sanctioned?
A new JSA claim may be refused because the claimant does not meet the eligibility requirements. Payments can also later be reduced or stopped because circumstances change or a sanction is imposed.
Reasons can include:
- Not Having Enough Qualifying National Insurance Contributions
- Working 16 Hours Or More Per Week
- No Longer Meeting Work-Search Requirements
- Missing Required Appointments Without Good Reason
- Turning Down Suitable Work Without Good Reason
- Failing To Attend Required Training
- Leaving Employment Without Good Reason
- Reaching The End Of The 182-Day Payment Period
A sanction is different from permanently cancelling a claim. It normally means payments are reduced or stopped for a particular period because the claimant did not meet an agreed requirement.
If someone believes a JSA decision is incorrect, they can normally ask for the decision to be reconsidered. Depending on the outcome, there may also be a right of appeal.
Claimants should provide accurate information and report changes promptly. Starting work, changes to income and other relevant circumstances should be reported to Jobcentre Plus.
Frequently Asked Questions
Can I Claim JSA With £10,000 in Savings?
Yes. £10,000 in savings does not prevent someone from receiving New Style JSA.
Eligibility depends primarily on National Insurance contributions and the other qualifying conditions rather than the amount held in savings.
Can I Claim JSA With More Than £16,000?
Potentially, yes. New Style JSA does not have the £16,000 capital limit associated with Universal Credit and legacy means-tested benefits.
Someone with more than £16,000 may qualify if they meet the contribution and eligibility rules.
Can Savings Cause My New Style JSA to Stop?
Savings themselves do not normally cause New Style JSA to stop.
Payments are more likely to end because the claimant reaches the 182-day limit, starts working 16 or more hours per week, no longer satisfies eligibility rules or receives a sanction.
Can My JSA Stop If My Partner Starts Working?
A partner starting work does not automatically end New Style JSA because a partner’s income and savings are not used in the same way as they are for means-tested benefits.
However, their earnings could affect any Universal Credit the household receives.