How Much Can I Earn on Universal Credit in 2026?
There is no single maximum amount that everyone can earn while receiving Universal Credit in 2026. Instead, the amount you receive normally reduces as your earnings increase.
How quickly it falls depends on whether you qualify for a work allowance and how much Universal Credit your household is entitled to before earnings are taken into account.
Universal Credit is calculated for each monthly assessment period. For every £1 of earnings taken into account above any applicable work allowance, your Universal Credit normally falls by 55p.
Some people can therefore work full-time and continue receiving a Universal Credit payment, while someone with a smaller maximum award may stop qualifying at a much lower income.
Is There a Maximum Earnings Limit for Universal Credit?
Universal Credit does not have one fixed salary or monthly earnings limit that applies to every claimant.
Instead, your award gradually reduces as your earnings rise.
Once the earnings reduction is large enough to reduce your Universal Credit entitlement to £0, you will no longer receive a payment for that assessment period.
The earnings level at which this happens varies according to factors including:
- Your Maximum Universal Credit Award
- Whether You Have Children
- Whether You Receive Help With Housing Costs
- Whether You Have Limited Capability For Work
- Whether You Are Claiming As A Couple
- Whether You Qualify For A Work Allowance
- Your Earnings During The Assessment Period
For this reason, two people earning the same salary can receive very different amounts of Universal Credit.
What Is The Universal Credit Work Allowance In 2026?
The work allowance is an amount certain Universal Credit households can earn before the 55% earnings reduction begins.
For the 2026/27 benefit year, the monthly work allowances are:
Circumstance Monthly Work Allowance
You receive help with housing costs through Universal Credit £427
You do not receive help with housing costs through Universal Credit £710
A work allowance is not available to every person receiving Universal Credit.
You normally qualify if you or your partner either have responsibility for a child or have limited capability for work.
Someone who does not meet the conditions generally has no work allowance. Their Universal Credit can therefore start reducing from the first £1 of earnings taken into account.
A household does not receive two separate work allowances simply because both partners are working.
How Does The 55% Universal Credit Taper Rate Work?
The Universal Credit taper rate is 55%.
This means Universal Credit generally reduces by 55p for every £1 of earnings that is subject to the taper.
For example, suppose a claimant receives housing support through Universal Credit and qualifies for the £427 work allowance.
If they have £1,200 of relevant earnings during an assessment period:
- Earnings: £1,200
- Work Allowance: £427
- Earnings Subject To The Taper: £773
- 55% Of £773: £425.15
Their Universal Credit would therefore be reduced by approximately £425.15 because of those earnings.
If the same person earned only £427 during that assessment period, earnings would not normally produce a taper reduction because they had not exceeded their work allowance.
However, someone who does not qualify for a work allowance would normally have the 55% taper applied from the beginning of their relevant earnings.
At What Earnings Level Will Universal Credit Stop?
There is no standard earnings figure at which Universal Credit stops because each household begins with a different maximum entitlement.
Someone receiving only the standard allowance may reach £0 considerably sooner than a household receiving additional amounts for children, housing costs or other qualifying circumstances.
A simplified way of understanding the calculation is:
Without a work allowance:
Maximum Universal Credit entitlement ÷ 55%
With a work allowance:
Work allowance + maximum Universal Credit entitlement ÷ 55%
For example, if a person’s maximum Universal Credit before the earnings deduction were £700 and they had no work allowance:
£700 ÷ 0.55 = approximately £1,272.73
On a simplified calculation, relevant earnings of around £1,272.73 could produce a £700 earnings deduction and reduce that award to £0.
This should only be treated as an illustration. Actual Universal Credit calculations can also be affected by other income, deductions and changes in household circumstances.
What Happens To Universal Credit If My Earnings Are Completely Cut Off?
If your earnings stop completely, Universal Credit will usually respond to the reduction in income.
For example, if you lose your job and have no earnings during the relevant assessment period, there may no longer be an earnings deduction from your award.
This can result in a higher Universal Credit payment, depending on your circumstances.
The increase is not necessarily immediate on the day your employment ends.
Universal Credit works through monthly assessment periods, so when your final wages are received can make a significant difference.
A final salary payment, payment in lieu of notice, holiday pay or other earnings received during an assessment period may still be taken into account.
If you stop working, you should also report the relevant change through your Universal Credit account when required.
Losing your earnings can also change your work-related requirements. Depending on your circumstances, you may be expected to look for work or take other steps under your claimant commitment.
What Happens If My Earnings Suddenly Drop?
Universal Credit is designed to adjust when earnings change.
If your earnings fall in a particular assessment period, the earnings deduction normally falls as well. As a result, your Universal Credit can increase.
This can happen if:
- Your Working Hours Are Reduced
- You Move To A Lower-Paid Job
- You Receive Less Overtime
- You Have Irregular Working Hours
- You Stop Work
- Your Employer Pays You Less During An Assessment Period
However, the timing of your wages is important.
Someone whose earnings have dropped may still receive a lower Universal Credit payment if earlier wages were paid during the same assessment period.
Universal Credit therefore does not simply look at your current annual salary. It considers the earnings falling within each monthly assessment period.
How Much Can A Couple Earn On Universal Credit?
Couples claiming Universal Credit are generally assessed as one household.
There is no separate maximum earnings limit for each partner. Earnings from both partners can affect the joint Universal Credit calculation.
If both partners work, their relevant earnings are considered when calculating how much Universal Credit the household should receive.
The household may qualify for a work allowance if the relevant conditions are met, but couples do not normally receive two separate work allowances.
For example, if one partner earns £1,000 and the other earns £800 during an assessment period, the household’s combined earnings will be relevant to the Universal Credit calculation.
Whether the couple continues receiving Universal Credit will depend on their maximum award and circumstances rather than simply whether either partner has crossed a particular salary limit.
Does Universal Credit Use Gross Pay Or Take-Home Pay?
For the calculation of employed earnings, Universal Credit generally takes account of pay after certain deductions, including Income Tax, employee National Insurance contributions and qualifying pension contributions.
This means the figure used for the Universal Credit earnings calculation is not always the same as the gross salary shown at the top of a payslip.
Employers normally report employee earnings to HMRC through the PAYE Real Time Information system. This information is then used in calculating Universal Credit.
Not every deduction from wages reduces the earnings figure used for Universal Credit.
Claimants should therefore avoid assuming that their bank deposit after every possible payroll deduction will always be the exact amount used in the calculation.
The rules for self-employed earnings are different because claimants usually have to report their business income and allowable expenses.
What Is The Administrative Earnings Threshold In 2026?
The Administrative Earnings Threshold, commonly known as the AET, is separate from the Universal Credit work allowance.
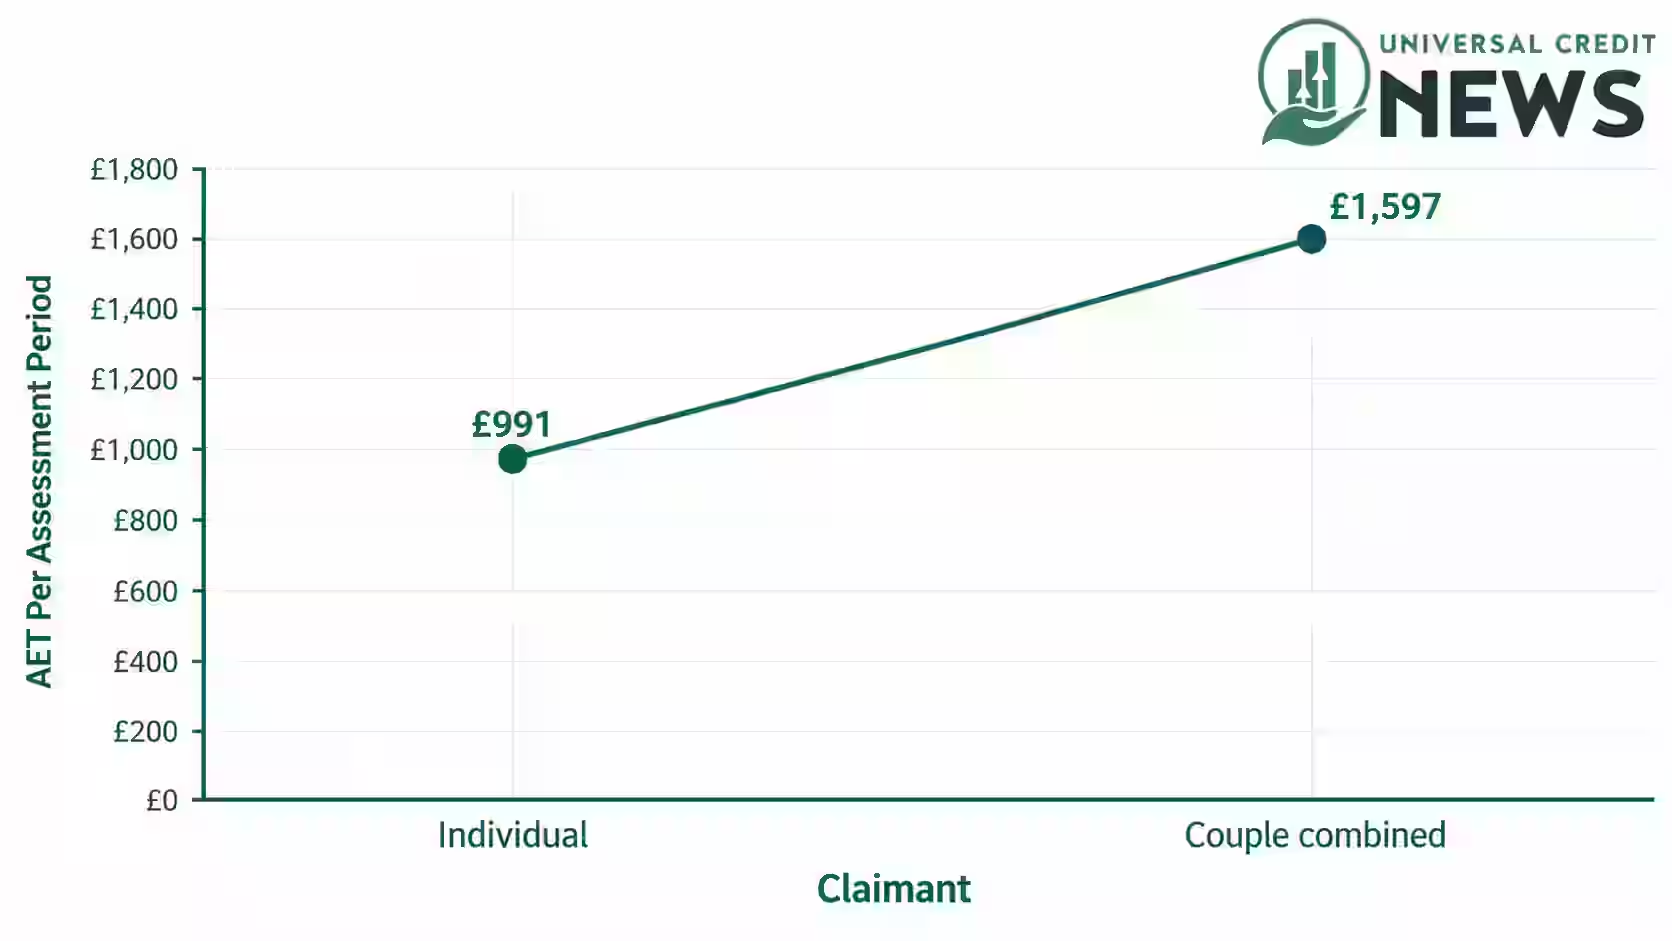
From April 2026, the AET is:
Claimant AET Per Assessment Period
Individual £991
Couple combined £1,597
The AET is based on earnings before deductions for Income Tax, National Insurance and qualifying pension contributions.
Importantly, £991 is not the amount you can earn before Universal Credit starts reducing.
The AET mainly affects the work-related requirements placed on claimants.
People earning below the relevant threshold may be expected to look for more work, increase their hours or seek higher earnings where the rules require them to do so.
The work allowance, by contrast, determines whether an eligible household can have some earnings before the 55% taper begins.
Confusing these two figures can lead claimants to wrongly believe that everyone can earn £991 without affecting Universal Credit.
Why Can Universal Credit Change Even If My Salary Has Not Changed?
Universal Credit is calculated according to the earnings received during each assessment period rather than simply using your stated annual salary.
This means your payment can occasionally change even when your normal rate of pay remains the same.
Problems can arise when someone:
- Gets Paid Twice During One Assessment Period
- Receives No Wages During Another Assessment Period
- Is Paid Weekly
- Is Paid Fortnightly
- Is Paid Every Four Weeks
- Has A Payday Brought Forward
- Receives Variable Monthly Earnings
For example, a person paid monthly might occasionally have two salary payments counted in one assessment period because a normal payday was moved due to a weekend or bank holiday.
The higher earnings recorded for that assessment period can reduce that month’s Universal Credit, even though the person’s underlying salary has not increased.
What Happens If I Get Overtime, Commission Or A Bonus?
Overtime, commission and bonuses can affect Universal Credit because they are generally treated as earnings when they are paid.
If you normally earn £1,500 but receive an additional £500 bonus during one assessment period, the higher earnings can cause your Universal Credit for that period to fall.
The effect depends on whether you have a work allowance and the size of your existing Universal Credit entitlement.
The same principle applies to overtime.
A claimant who works extra hours during Christmas, takes on additional shifts or earns performance-related commission may receive less Universal Credit for the assessment period in which those earnings are counted.
If the additional income does not continue, Universal Credit may increase again when earnings fall in a later assessment period.
How Do Self-Employed Earnings Affect Universal Credit?
Self-employed claimants have different reporting requirements from employees.
They generally need to report business income and allowable expenses for every monthly reporting period, including periods where they had no business income or expenses.
Some people considered gainfully self-employed can also be affected by the Minimum Income Floor.
The Minimum Income Floor is an assumed earnings amount. Where it applies and someone’s actual earnings are below the Minimum Income Floor, Universal Credit may be calculated using the higher Minimum Income Floor figure instead.
This means a self-employed claimant could earn very little during one month without receiving the same increase in Universal Credit that an employee with similarly low earnings might expect.
However, eligible newly self-employed claimants can receive a start-up period of up to 12 months.
During an eligible start-up period, the Minimum Income Floor does not apply and Universal Credit is calculated using actual monthly self-employed earnings.
Claimants are expected to continue taking active steps to build their business.
What Happens If My Universal Credit Reaches £0 Because Of Earnings?
As wages increase, Universal Credit gradually reduces. Eventually, earnings may be high enough to reduce the award to £0.
Receiving £0 because of earnings does not mean you are permanently prevented from getting Universal Credit again.
If earnings subsequently fall, entitlement can return.
This can be particularly important for people with variable work, temporary contracts, seasonal employment or irregular overtime.
The exact result still depends on the earnings recorded during the relevant assessment period and whether anything else affecting the claim has changed.
Where unusually high earnings are received, additional rules can sometimes cause earnings from an earlier period to affect a later Universal Credit calculation.
Can Universal Credit Restart If My Earnings Fall Again?
Yes. Universal Credit can restart if your earnings fall after previously becoming too high for you to receive a payment.
If it has been six months or less since your last Universal Credit payment, payments can normally restart automatically once your earnings fall sufficiently and you become entitled again.
If more than six months have passed since your last Universal Credit payment, you will generally need to make a new Universal Credit claim.
This is particularly useful for workers whose income is not stable throughout the year.
For example, someone may temporarily earn enough through overtime or seasonal work for their Universal Credit payment to fall to £0.
If the extra work ends and their earnings fall again within the relevant period, their Universal Credit may begin paying again without a completely new application.
The amount still depends on the household’s circumstances and earnings during each assessment period.
FAQs
Can I Work Full-Time And Still Get Universal Credit?
Yes. There is no general rule preventing someone from receiving Universal Credit because they work full-time. Whether you receive a payment depends mainly on your earnings and household entitlement.
How Much Can I Earn Before Universal Credit Starts To Reduce?
If you qualify for a work allowance in 2026/27, it is £427 a month if you receive qualifying housing support through Universal Credit or £710 if you do not. Without a work allowance, earnings can affect UC from the first £1.
What Happens To Universal Credit If I Have No Earnings?
If your earnings fall to £0, your earnings deduction may also disappear, which can increase your Universal Credit. The timing of final wages and your assessment period can affect when this happens.
Does Universal Credit Increase Automatically If I Lose My Job?
It can increase when reported earnings fall, but Universal Credit calculations are based on assessment periods. Final wages received after leaving a job can still affect the next payment.
Do Both Partners’ Wages Count On A Joint Universal Credit Claim?
Yes. Universal Credit assesses couples as a household, so earnings from both partners can affect the joint award.
Can Universal Credit Restart If My Wages Drop?
Yes. If your last Universal Credit payment was six months or less ago, payments can normally restart automatically if your earnings drop enough for you to qualify again.